Mortgage financing can be complicated & stressful.
It doesn't have to be, let me show you how!
GET STARTED
Mortgage Financing in Creston B.C

MORTGAGE FINANCING IN THREE EASY STEPS

Connect With Me

The best place to start is to connect with me directly. The mortgage process is personal. My commitment is to listen to all your needs, assess your financial situation, and provide you with a plan to move forward. 


Consider Your Options

Once we’ve had a look at your financial situation, we’ll consider a variety of mortgage options, I’ll outline what is necessary to qualify for your mortgage, negotiate with the lenders on your behalf, and arrange the mortgage that best suits your needs.

Rest Easy

Once we’ve arranged financing with the best lender and the property is yours, you’re not on your own. My goal is to be your mortgage professional for life! Any questions in the years to come, contact me anytime! 


THANK YOU for two years in a row of being Readers Choice best mortgage broker.

Lori LaLonde

With over 20 years of experience helping families across BC with mortgage financing, I would love to assist you in making your homeownership dreams a reality while saving you as much money as possible.

I moved to the beautiful community of Creston, BC in March 2024, and have completely fallen in love with Creston and the valley. While Creston is now proudly my home, I am still able to assist clients anywhere in BC, bringing the same care and expertise I’ve always offered.

I specialize in serving the mortgage needs of clients here in Creston and the Kootenays, while also supporting families relocating within BC or Alberta. Whether you’re purchasing your first home, refinancing, or investing in property, I can help put together a plan that gets you exactly where you want to be.

If you’re looking for a mortgage broker with years of experience, a wealth of industry connections, and a personal commitment to your success, please don’t hesitate to contact me anytime!

READ MORE

A Huge Thank You —

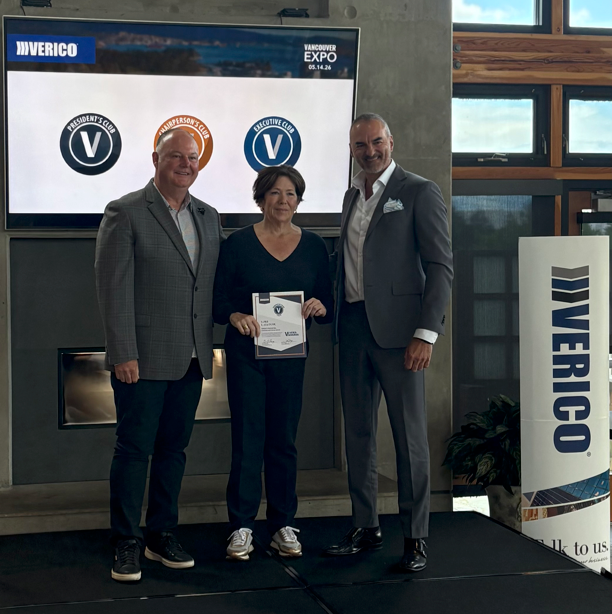
VERICO Executive Club Award 2025

This recognition means the world to me, and it truly belongs to every person who trusted me with their mortgage journey this past year.

To my incredible clients in Creston, the Kootenays, and across BC — thank you. Your trust is the foundation of everything I do, and I don't take it lightly. Whether you were buying your first home, renewing, or navigating something more complex, it was a privilege to be in your corner.


To my referral partners, realtors, and the amazing community here in Creston — your support and word-of-mouth mean more than I can say. Creston has welcomed me so warmly, and I am proud every single day to call this valley home.


Here's to doing it all over again in 2026. 🙌
Nice things people have said about working with me.

"I personally used Lori to purchase my latest income property, not only was Lori fast and professional, she was able to provide me with more insight than anyone I have previously worked with. I appreciate her professionalism and willingness to tell it like it is."

LAURA W.

"I have worked with Lori on several occasions and have found her to be extremely fast at getting back to me, exceptionally professional in her dealings with me and the clients as well as being very knowledgeable of the products and services she provides."

CARY R.

"We have been using Lori Lalonde for close to two decades. Lori has been a beacon of light through the murky waters of home financing. She has always taken the time to explain pieces we don't understand, even if she has explained them before :). We have purchased two properties and been through a few refinances to capitalize on better rates, of which Lori has brought to our attention. She always provides lots of options and consultation and ensures that we understand the implications of our decisions. Lori is wonderful mortgage broker and extremely competent. I would, have and will again recommend Lori to anyone looking for a mortgage broker."

Greg Fraser

"Lori went above and beyond when I was looking to refinance my mortgage. She was patient, always available, answered all my questions and explained all my options. I would highly recommend Lori."

Jordan Hurdal

"Working with Lori was a great experience. Very thorough, knowledgeable, and went way above and beyond for my family and I."

Colin Campbell

John Doe's Image
Lori has been amazing to work with, she is very patient and has adapted for me in many situations to provide whats best for me

Lori is a quick worker she was able to get me 2 mortgages when the big banks denied!

I Highly recommend Lori Lalonde if your wanting a new mortgage!

Thank you again for all your hard and amazing work Lori, I cant thank you enough

Derek

Get started by completing my online mortgage application.

I'll let you know exactly where you stand so you can proceed with confidence.

APPLY NOW

Mortgage articles to keep you informed.
By Lori Lalonde September 15, 2026
Cashback Mortgages: Are They Worth It? Here’s What You Need to Know If you’ve been exploring mortgage options and come across the term cashback mortgage , you might be wondering what exactly it means—and whether it’s a smart move. Let’s break it down in simple terms. What Is a Cashback Mortgage? A cashback mortgage is just like a regular mortgage—but with one extra feature: you receive a lump sum of cash when the mortgage closes . This cash is typically: A fixed amount , or A percentage of the total mortgage , usually between 1% and 7% , depending on your mortgage term and lender. The money is tax-free and paid directly to you on closing day. What Can You Use the Cashback For? There are no restrictions on how you use the funds. Here are some common uses: Covering closing costs Buying new furniture Renovations or home upgrades Paying off high-interest debt Boosting your cashflow during a tight transition Whether it’s to help you settle in or catch up financially, cashback can offer a helpful buffer— but it comes at a cost . The True Cost of a Cashback Mortgage Here’s the part many people overlook: cashback mortgages come with higher interest rates than standard mortgages. Why? Because the lender is essentially advancing you a small loan upfront—and they’re going to make that money back (and then some) through your mortgage payments. So while the upfront cash feels like a bonus, you’ll pay more in interest over time to have that convenience. Breaking Down the Numbers It’s hard to give a blanket answer about how much more you’ll pay since it depends on: Your interest rate The cashback amount The mortgage term Your payment schedule This is why it’s important to run the numbers with a mortgage professional who can help you compare this option with others based on your personal financial situation. Are You Eligible for a Cashback Mortgage? Not everyone qualifies. Cashback mortgages generally come with stricter requirements . Lenders often want to see: Excellent credit history Strong, stable income Low debt-to-income ratio If your mortgage file includes anything “outside the box”—like being self-employed or recently changing jobs—qualifying for a cashback mortgage might be tough. What If You Need to Break the Mortgage? This is one of the biggest risks with cashback mortgages. If your circumstances change and you need to break your mortgage early, you could be on the hook for: Paying back some or all of the cashback you received, and A prepayment penalty (typically the interest rate differential or 3 months’ interest—whichever is higher) That can be a very expensive combination. So if there’s even a chance you might need to sell, refinance, or move before your term is up, a cashback mortgage might not be the best fit. Should You Consider a Cashback Mortgage? Maybe—but only with eyes wide open. Cashback mortgages can be helpful in the right scenario, but they’re not free money. They’re a lending tool that benefits the lender , and the key is knowing exactly what you’re agreeing to. Final Thoughts: Talk to an Expert First Choosing the right mortgage isn’t just about the lowest rate or the biggest perk—it’s about making a choice that fits your whole financial picture. If you’re considering a cashback mortgage, or just want to explore all your options, let’s talk. As an independent mortgage professional , I can help you weigh the pros and cons of various products, so you can make a confident, informed decision. Have questions? I’d be happy to help—reach out anytime.
By Lori Lalonde September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By Lori Lalonde September 1, 2026
Don’t Forget About Closing Costs When planning to buy a home, most people focus on saving for the down payment. But the truth is, that’s only part of the equation. To actually finalize the purchase, you’ll also need to budget for closing costs —the out-of-pocket expenses that come up before you get the keys. Closing costs can add up quickly, which is why they should be part of your pre-approval conversation right from the start. Lenders will even require proof that you’ve got enough funds set aside. For example, if you’re getting an insured (high-ratio) mortgage, you’ll need at least 1.5% of the purchase price available in addition to your down payment. That means a 10% down payment actually requires 11.5% of the purchase price in cash to make everything work. Let’s break down some of the most common expenses you should prepare for: 1. Home Inspection & Appraisal Inspection : Paid by you, this gives peace of mind that the property is in good shape and doesn’t have hidden problems. Appraisal : Required by the lender to confirm value. Sometimes this is covered by mortgage insurance, sometimes by you. 2. Legal Fees A lawyer or notary is required to handle the title transfer and make sure the mortgage is properly registered. Legal fees are often one of the larger closing costs—unless you’re also responsible for property transfer tax. 3. Taxes Many provinces charge a property or land transfer tax based on the home’s purchase price. These fees can range from hundreds to thousands of dollars, so you’ll want to factor them in early. 4. Insurance Property insurance is mandatory—lenders won’t release funds without proof that the home is insured on closing day. Optional coverage like mortgage life, disability, or critical illness insurance may also be worth considering depending on your financial plan. 5. Moving Costs Whether you’re renting a truck, hiring movers, or bribing friends with pizza and gas money, moving comes with expenses. Cross-country moves especially can be surprisingly pricey. 6. Utilities & Deposits Setting up new services (electricity, water, internet) can involve connection fees or deposits, particularly if you don’t already have a payment history with the utility provider. Plan Ahead, Stress Less This list covers the big-ticket items, but every purchase is unique. That’s why it pays to have an accurate estimate of your personal closing costs before you make an offer. If you’d like help planning ahead—or want a breakdown tailored to your situation—let’s connect. I’d be happy to walk you through the numbers and make sure you’re fully prepared.

Everything you need, all in one place

As a trusted mortgage provider, let me help you with these services.

Click through any of the services to learn more